
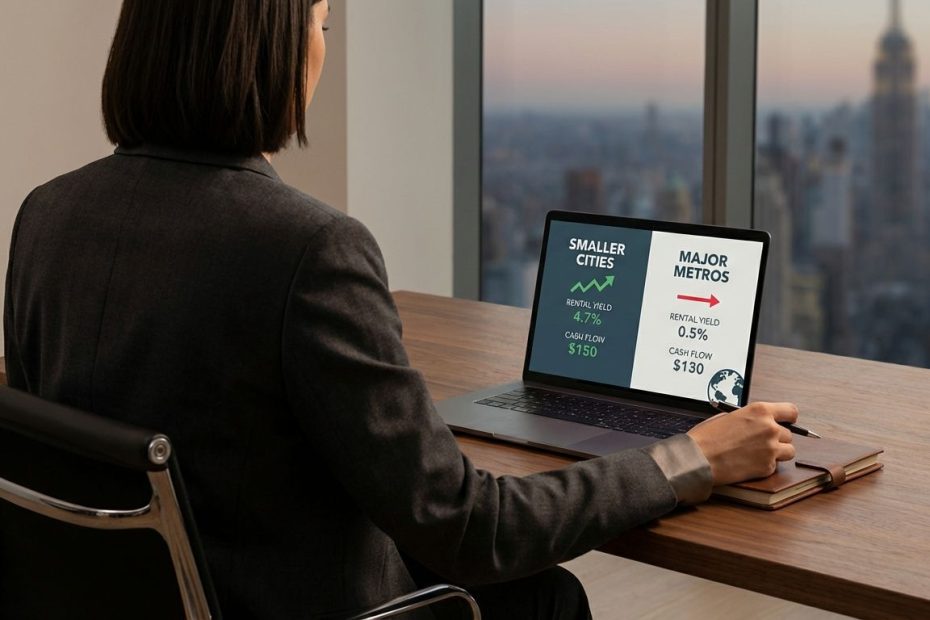
The most profitable real estate often shows up where your purchase price stays grounded but rents stay resilient, and that combination is frequently easier to find outside major cities. Big-city property can still build wealth, but it often delivers slimmer rental yield, higher carrying costs, and tighter margins that force you to rely on appreciation to make the numbers work.
This guide helps you decide where profits really come from, cash flow or total return, and how to compare a major metro deal to a smaller-city deal using the same underwriting lens. You’ll walk away knowing which metrics matter most, how to spot “fake” yield, and how to build a market selection process that fits your risk tolerance and time commitment.
Why Can Real Estate In Smaller Cities Be More Profitable Than Property In Major Cities?
Profit in rentals is a spread business. When the gap between rent and your all-in cost basis is wide, you can pay the mortgage, fund reserves, absorb vacancies, and still keep cash flow. In many smaller or secondary markets, purchase prices sit low enough that achievable rents produce stronger gross yields than what you typically see in high-demand coastal and gateway metros. That’s the simple math that keeps pulling disciplined investors away from the “headline cities.”
ATTOM’s 2025 single-family rental market report puts hard numbers behind the pattern. Across the 361 counties analyzed, the projected annual three-bedroom gross rental yield averages 7.45% in 2025, down slightly from 7.52% in 2024, with yields declining in nearly 60% of those counties as prices rise faster than rents. The report also shows how widely yields can vary, with some large, expensive areas producing very low yields while many non-gateway markets still post yields that can support cash-flow investing. Those yield spreads are where “boring” markets can quietly outperform.
Another reason smaller markets can win is that competition looks different. Major cities attract capital that accepts lower cap rates in exchange for perceived safety, strong liquidity, and long-term demand. When buyers bid up prices faster than rents can follow, your yield compresses and your deal becomes more sensitive to interest rates, taxes, insurance, and maintenance surprises. Smaller cities do not automatically mean “easy,” but they often let you buy margin, and margin is what keeps you in the game when the market stops cooperating.
Is It True That Renting Is Cheaper Than Owning In Big Metros, And How Does That Affect Investment Returns?
Yes, and it matters more than most investors admit. An Axios analysis published February 2, 2026 reports that renting is cheaper than owning in every major U.S. metro, with the median monthly gross rent nearly $1,500 in 2024 compared with over $2,000 a month for mortgaged homes. It also notes that in 22 of the 100 largest metros, owning costs at least 50% more each month than renting when utilities, fees, and taxes are included. When the cost to own runs that far ahead of the cost to rent, investors frequently face the same imbalance: asset prices outrun rent fundamentals.
When owning gets expensive relative to renting, rental demand can stay strong, but that does not automatically improve investor returns. In high-priced metros, the rent you can charge often cannot “catch up” to the purchase price you have to pay, especially when insurance, HOA fees, and property taxes stack up. That pushes many investors into appreciation-dependent strategies, where the deal may break even or run slightly negative after reserves, and the win comes from equity growth over time.
Outside major cities, the relationship can flip in your favor. Lower entry prices can produce a healthier rent-to-price relationship, which gives you room to underwrite conservatively and still see cash-on-cash returns that feel like real investing, not speculation. It also gives you flexibility: you can refinance, you can fund CapEx without sweating, and you can survive a rent softening period without selling at the wrong time.
What Metrics Actually Predict Profitability Outside Major Cities?
Start with rent-to-price as a screening tool, then make operating reality do the final decision. Rent-to-price and gross yield help you identify where a property might cash flow, but expenses and execution determine whether it actually does. Investors who rely on one rule-of-thumb end up surprised by taxes, insurance, maintenance, turnover, and local management issues that were never priced into the “back of the napkin” math.
Use a stack of metrics that work together. Track gross yield and cash-on-cash return, then pressure-test with vacancy assumptions, expense ratios, reserve funding, and rent growth ceilings. Realtor.com’s September 2025 rental report highlights rent share of income by metro and shows meaningful differences in affordability across markets, with some expensive metros carrying very high rent burdens. High rent burden can raise delinquency risk and increase political pressure for tenant-friendly rules, and it also limits how aggressively rent can grow without pushing renters out.
Also measure the “deal survivability” metrics that investors skip when they are chasing yield. A deal survives when you can handle vacancy, repairs, and slow leasing without injecting cash or panicking into a sale. CBRE’s U.S. Real Estate Market Outlook 2026 notes the overall multifamily vacancy rate is 4.4%, below the 2010–2019 average of 5.2%, and expects vacancy to rise over the next several quarters as supply delivers. It also notes renewals are 57% of leasing activity, which underscores a practical underwriting point: your retention strategy and renewal economics matter, and the best market in the world will still punish sloppy operations.
What Are Real Data Examples Of Non-Major Markets Outperforming Big Cities On Cash Flow?
Look at affordability and yields side-by-side and the story becomes hard to ignore. Visual Capitalist’s 2025 affordability mapping shows home price-to-income ratios across major North American metros, with Los Angeles at 10.7 and Detroit at 3.8 based on benchmark prices as of July 2025 and median household income. A lower price-to-income ratio often signals a market where rents have a better chance to cover ownership costs, even if rent growth is slower than in a glamour metro.
Redfin’s 2025 housing market year-in-review states Detroit was the most affordable major metro for homebuyers in 2025, with the median sale price averaging $202,739. That affordability is exactly why cash-flow investors keep circling markets like Detroit, Cleveland, and Pittsburgh: you can buy an asset at a price point where rent has a fighting chance to produce real yield, then you can build a portfolio with smaller down payments and less concentration risk per door.
ATTOM’s 2025 report goes further by naming specific high-yield counties and also calling out low-yield areas. It lists top projected three-bedroom gross rental yields in 2025 including Suffolk County, NY (18%), Atlantic County, NJ (16.8%), Jefferson County, AL (13.6%), Mobile County, AL (12.9%), and Ector County, TX (12.5%). On the low end, it cites Santa Clara County, CA (2.9%) and San Mateo County, CA (3.3%), which captures the major-city problem in one line: purchase prices can get so inflated that rent becomes a weak support beam for your return.
Market media aimed at active investors also reflects where the math still works. BiggerPockets’ 2025 cash flow markets coverage highlights smaller metros and publishes rent-to-price ratios, including an “honorable mention” of Ocala, FL with a median price of $259,900, median rent of $1,636, and a rent-to-price ratio of 0.63%. That ratio alone does not guarantee a good deal, but it shows why investors hunting for income keep looking outside the biggest cities, where rent-to-price often falls below what conservative underwriting requires.
What Are The Biggest Hidden Risks Of Investing For Yield In Small Cities, And How Do You Reduce Them?
High yield is rarely “free.” In many small-city and tertiary-market deals, the extra return is compensation for real friction: tenant quality variance, higher turnover, maintenance intensity, weaker contractor networks, slower leasing in pockets that are street-by-street, and less forgiving resale liquidity. If you buy purely off a spreadsheet and ignore the operational load, a cheap house can become an expensive lesson.
ATTOM’s yield rankings make an important point between the lines: yields differ dramatically, even within large metro areas, and they can shift year to year as prices outrun rents. In 2025, ATTOM notes yields fell from 2024 to 2025 in many markets because prices rose faster than rents in 54% of the areas they studied. When you enter a high-yield market late in a price run-up, the “cheap market” can stop being cheap, and your margin shrinks faster than most investors adjust their underwriting.
Risk control comes from discipline, not optimism. Underwrite higher reserves than you want to, assume longer turns than the property manager promises, and price your renovation scope for durability, not for the cheapest initial bid. Also demand clarity on eviction timelines, local court speed, and property tax reassessment behavior. A smaller market can be extremely profitable when you treat it like an operating business and keep your leverage within a range that lets you stay calm through a rough quarter.
Should You Choose A Major City For Appreciation Or A Smaller City For Cash Flow?
Choose the market that matches how you want to get paid. If the goal is monthly income that supports lifestyle or reinvestment, you need deals that generate cash flow after reserves, management, maintenance, vacancy, and realistic CapEx. That often means buying where the rent-to-price relationship is healthy, which is more common outside major cities and in selected neighborhoods of mid-size metros.
If the goal is long-term equity growth, liquidity, and easier exits, major cities can still work, but the underwriting needs to admit what is happening. In low-yield metros, you are commonly accepting thin cash flow and heavier interest-rate sensitivity, then relying on rent growth, wage growth, and long-run demand to carry the total return. CBRE’s 2026 outlook expects cap rates to be stable in 2026 with incremental compression later, and it flags operational challenges in high-supply markets. That is a reminder that even “safe” markets can deliver periods where your only job is to hold and operate well.
A strong operator can mix strategies without confusion. A smaller-city portfolio can fund itself and create optionality, and a carefully chosen major-city asset can anchor long-term appreciation and refinance options. Profitability improves when the strategy is explicit: cash-flow assets get judged on month-to-month performance, appreciation assets get judged on long-term demand and exit pricing, and neither gets evaluated using the wrong scoreboard.
Where Is Real Estate Most Profitable If Major Cities Don’t Cash Flow?
- Buy where rent-to-price supports reserves and debt service
- Target stable job centers, manageable taxes, strong leasing demand
- Avoid yield traps with high turnover and weak property management
Build Your Market Filter, Then Execute With Discipline
Profit shows up when purchase price, rent, and operating costs line up in your favor, and smaller cities often give you that alignment more often than major metros. Use data like ATTOM’s county-level yields to see where rent supports price, then validate the deal with vacancy, expense ratios, and a realistic CapEx plan. Keep affordability and income constraints in view, since price-to-income and rent burden can cap rent growth and increase default risk. Once the numbers work, operational execution decides the outcome, so lock in a reliable property manager, enforce screening standards, and fund reserves like a professional. The goal is not to own property in a famous zip code, the goal is to own assets that pay you for the risk you are taking.
References
- Axios (Feb 2, 2026): Renting is cheaper than owning in every major U.S. metro
- ATTOM (2025): Single Family Rental Market Report / Best Counties for Buying Single-Family Rentals in 2025
- Visual Capitalist (2025): Housing Affordability Across North America in 2025
- BiggerPockets (2025): The Top 3 Cash Flow Markets in 2025
- CBRE (2026): U.S. Real Estate Market Outlook 2026, Multifamily
- Realtor.com (Sep 2025): Rental Report, Rent Share of Income by Metro
- Redfin (2025): Housing Market Year In Review
- Zillow (Dec 2025): Rent Report
- Reddit: Trade-offs for rentals in cities with little cash flow
- Reddit: ROI of rentals in small cities compared to larger cities
- Reddit: Investing in low-income neighborhoods discussion
- Reddit: Detroit real estate guidance discussion
- Reddit: First-timer evaluating property discussion.

Chrysilios Chrysiliou is a commercial real estate executive at RDPH Properties, Inc. with a diverse background in aviation and entrepreneurship. A former Greek Air Force Academy graduate, flight instructor, and flight school co-owner, he now leverages decades of strategic leadership to identify and develop high-value real estate opportunities.